Introduction
Risk Snapshot
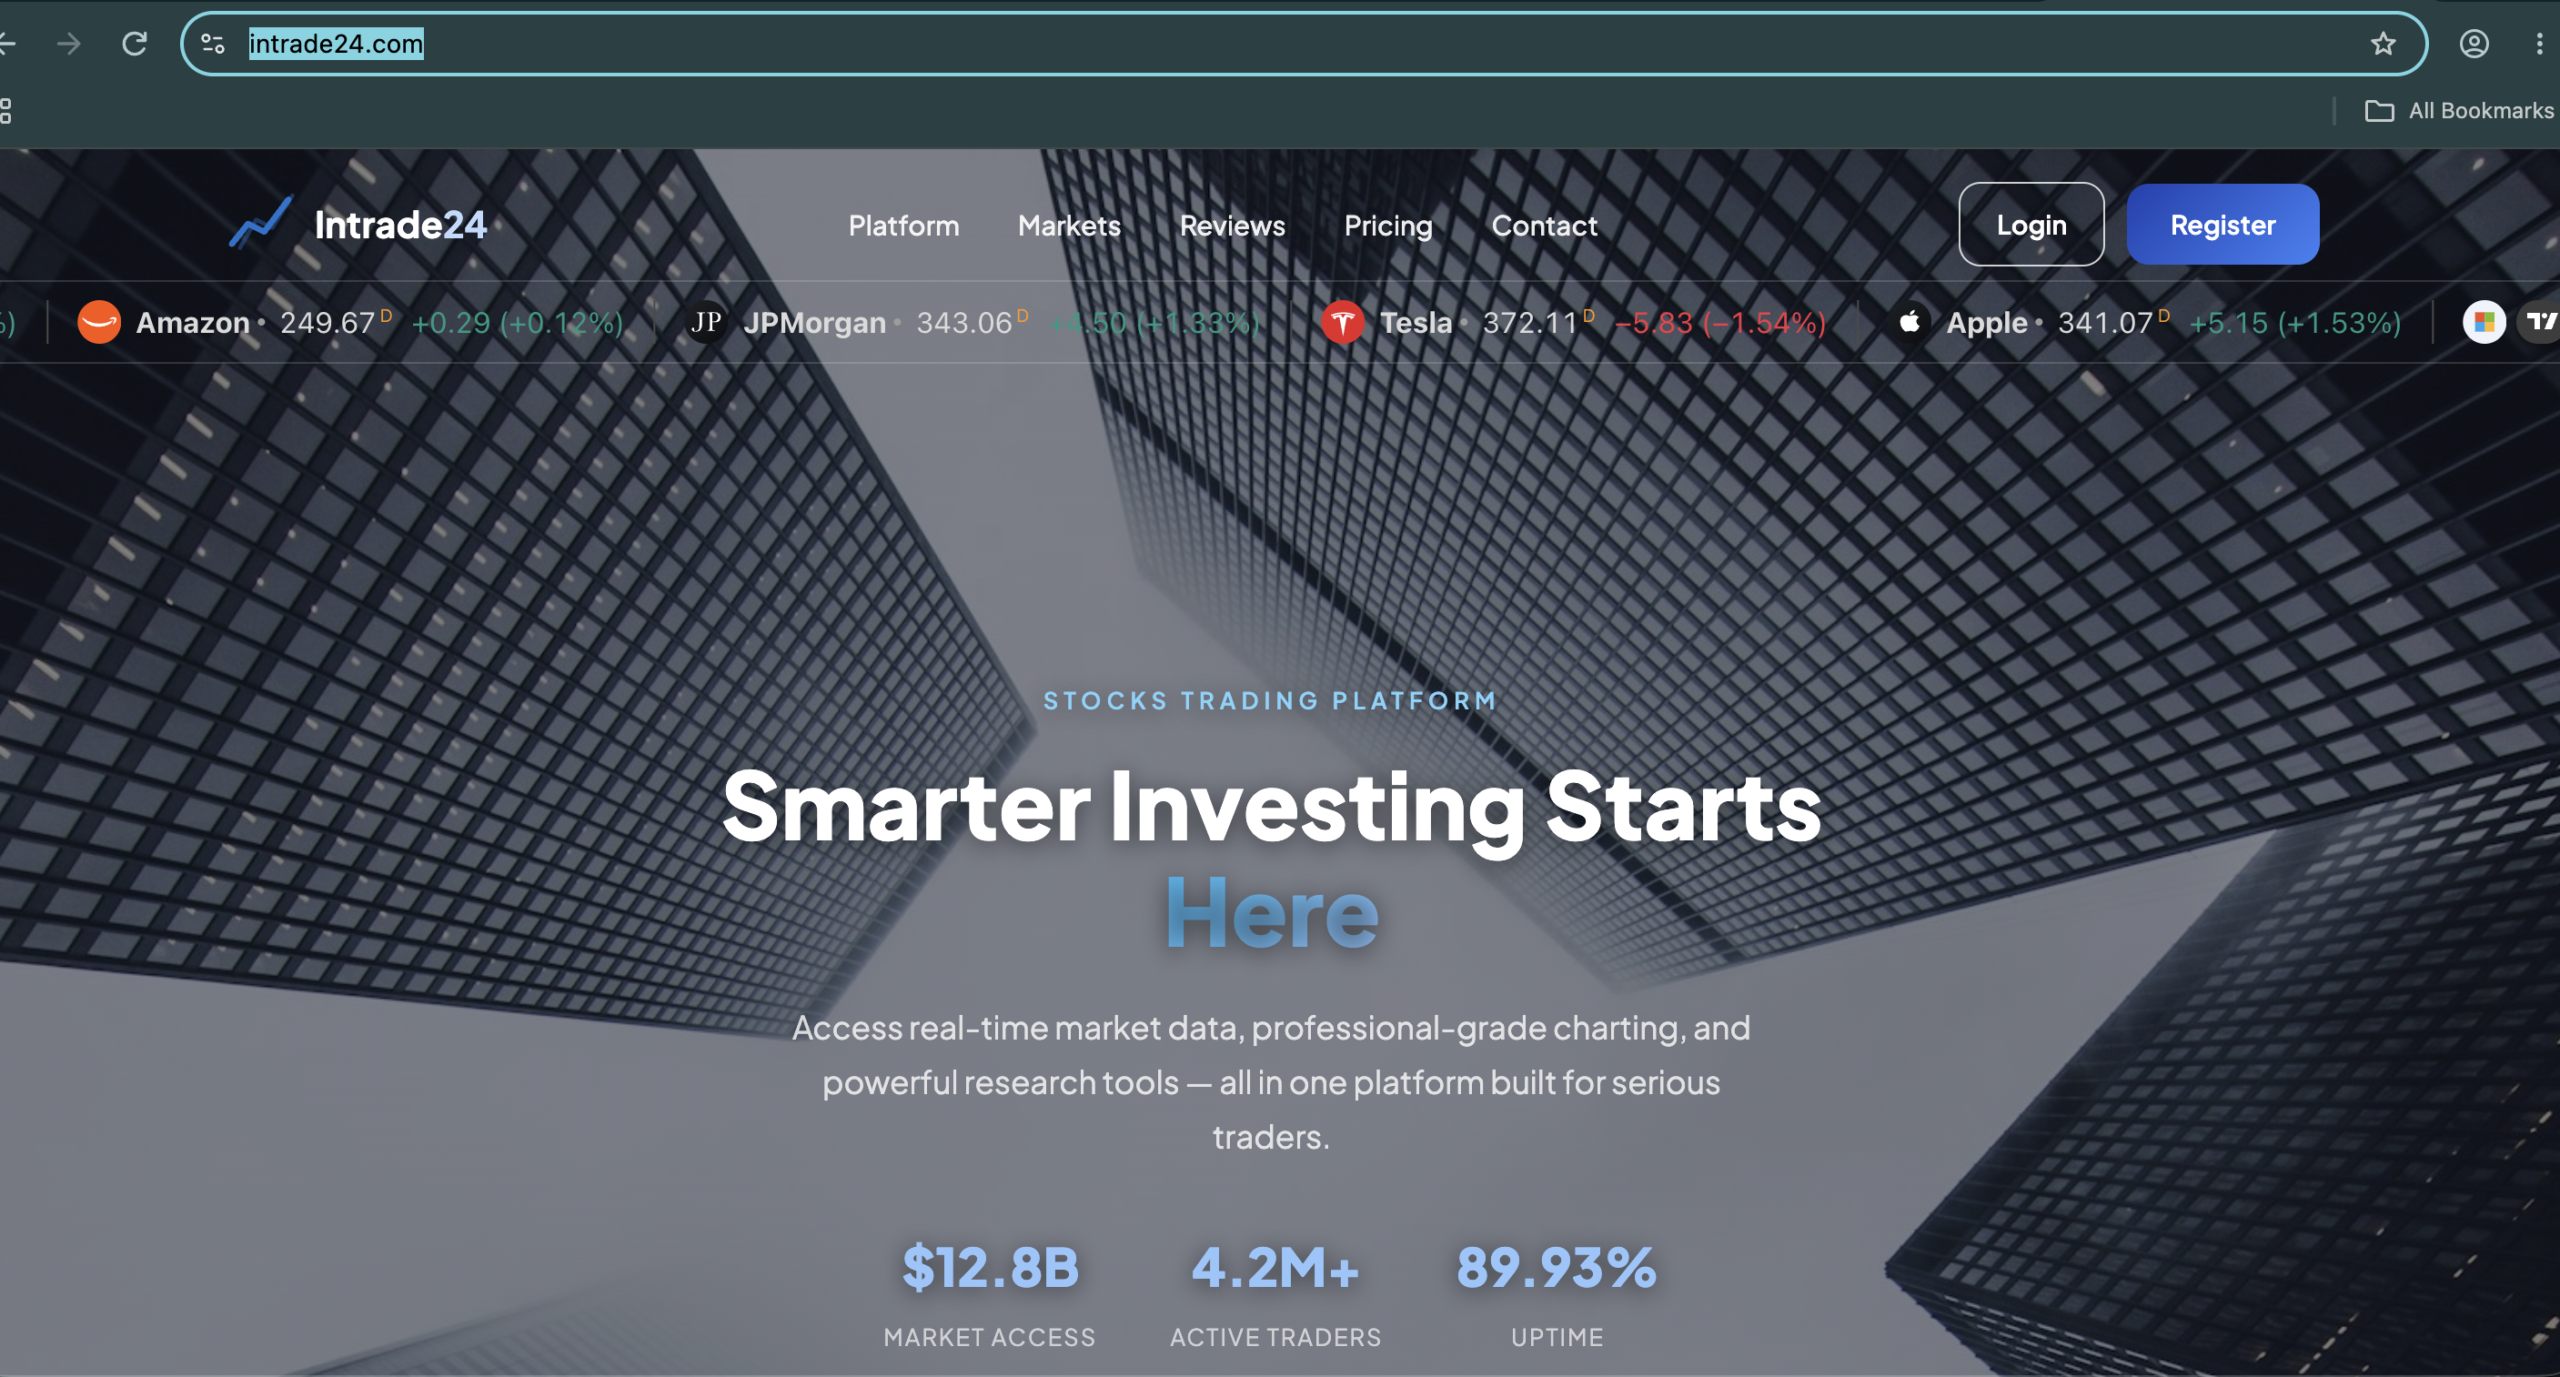
Platform: Intrade24
Alternative name: In Trade 24 Trust
Website identified by regulator: intrade24.com
Regulatory warning: Autorité des marchés financiers (AMF)
Warning date: 4 September 2026
Regulatory position: Not registered with the AMF and not authorised to solicit Québec investors
Risk category identified by the AMF: High-risk platform
The AMF’s warning is the central verified concern surrounding Intrade24.
This does not establish that every transaction or individual associated with the platform is fraudulent. It does mean that investors should not treat Intrade24 as a verified investment provider without conducting independent regulatory and corporate checks.
1. THE FIRST QUESTION INVESTORS SHOULD ASK
When an unfamiliar investment platform approaches an investor, the natural question is often:
“Can I make money with this platform?”
That is not the first question that should be asked.
The first question should be:
“Who is legally operating this platform, and are they authorized to provide these services to me?”
That distinction is particularly important with Intrade24.com because the AMF has specifically stated that the platform is not registered with it and is not authorised to solicit investors in Québec.
An attractive trading interface, convincing representative or apparently successful account does not replace regulatory authorization.
2. WHAT THE REGULATOR HAS ACTUALLY SAID
The AMF identifies the business as Intrade24, with In Trade 24 Trust listed as another business name.
Its warning identifies intrade24.com and classifies the platform as a high-risk platform.
The AMF states that Intrade24.com is not registered with the authority and is not authorized to solicit Québec investors.
This is an important distinction from an ordinary negative review.
A dissatisfied customer can post an online complaint based on a personal experience.
A securities regulator’s warning addresses the firm’s regulatory status within that regulator’s jurisdiction.
The AMF itself advises investors to consult its registers before dealing with an investment firm or individual and notes that its warning list is not exhaustive.
3. WHY THIS SHOULD MATTER TO AN INVESTOR
Imagine someone receives an offer to invest through an unfamiliar online trading platform.
The website looks professional.
A representative explains the markets confidently.
The account opens quickly.
The investor deposits money.
A dashboard shows the account increasing in value.
At this point, it can feel as though everything is working normally.
But none of those events answers the most important question:
Is the money actually being held by an authorized financial firm under an appropriate regulatory framework?
A website can display a balance without independently proving that the balance represents accessible funds.
A representative can provide information without being authorized to provide investment advice.
A company can have a corporate registration without having financial-services permission.
This is why independent verification is so important.
4. THE DIFFERENCE BETWEEN A COMPANY AND A REGULATED INVESTMENT FIRM
Investors sometimes see a company registration number and assume the investment platform has therefore been approved.
That is not necessarily the case.
There is a major difference between:
Company registration
and
Financial-services authorization.
A company can potentially exist as a registered business while not being authorised to provide regulated investment services in a particular country.
Investors should therefore verify both:
- the company’s legal existence; and
- its permission to provide the specific financial service being offered.
The second question is often the more important one.
5. THE WEBSITE SHOULD NOT BE YOUR MAIN SOURCE OF TRUST
One of the easiest mistakes to make is allowing the platform itself to become the primary source of information about the platform.
If the website says:
- “regulated”;
- “licensed”;
- “secure”;
- “trusted”;
- “professional”;
- “fully compliant”;
those claims should be independently checked.
The same applies to:
- regulatory logos;
- certificates;
- license numbers;
- company awards;
- claimed partnerships;
- trading statistics;
- testimonials.
A genuine license should be independently discoverable through the relevant regulator.
6. THE ACCOUNT BALANCE TEST
One of the most important lessons for investors is this:
A displayed balance is not the same thing as accessible money.
Suppose an investor deposits £4,000 and later sees:
Account balance: £11,850
It may appear that the investment has generated £7,850.
But the investor should not assume that figure represents cash sitting safely in a bank or regulated custodial account.
The important test is what happens when the investor asks for their money back.
That is why withdrawal procedures should be understood before a significant deposit is made.
7. WHEN A WITHDRAWAL BECOMES A PROBLEM
Be especially careful if a platform says you must make another payment before receiving your existing funds.
The explanation might be:
“You need to pay tax.”
“You need to complete verification.”
“Your account needs to be upgraded.”
“You need to provide liquidity.”
“There is an insurance requirement.”
“The withdrawal requires a release fee.”
“You need to pay a security deposit.”
A legitimate financial service can have genuine charges, so the existence of a fee alone is not proof of wrongdoing.
The important question is:
Can the claimed requirement be independently verified?
If the only person explaining the charge is the same representative who wants you to send the money, stop and investigate before paying.
8. PRESSURE IS A REASON TO PAUSE
Investors should be cautious when conversations begin to sound urgent.
Examples include:
- “You must deposit today.”
- “This opportunity closes tonight.”
- “The market is about to move.”
- “You are missing out.”
- “Deposit more to unlock greater profits.”
- “You have to upgrade before withdrawing.”
- “We can recover your losses if you invest again.”
The more pressure an investor experiences, the more important it becomes to slow down.
A legitimate investment decision should survive independent verification and reasonable consideration.
9. HOW TO CHECK AN UNFAMILIAR PLATFORM
Use this sequence:
IDENTITY
Find the exact legal company name.
JURISDICTION
Determine where that company is legally based.
REGULATOR
Identify the regulator responsible for financial services in that jurisdiction.
LICENCE
Verify the firm’s authorization independently.
PERMISSION
Check whether its licence actually covers the product being offered.
WEBSITE
Confirm that the regulator’s record corresponds with the website you are using.
MONEY
Determine exactly who receives your deposit.
CUSTODY
Establish who holds the investor’s funds.
WITHDRAWAL
Understand how funds can be withdrawn before depositing.
COMPLAINTS
Find out where an investor can make an independent complaint if something goes wrong.
If several answers remain unclear, that uncertainty itself is a reason to stop.
10. A SPECIAL CHECK FOR UK INVESTORS
If you are located in the UK, use the FCA Financial Services Register/Firm Checker before dealing with an unfamiliar investment provider.
Do not simply search for a similar company name.
Compare:
- legal entity;
- website;
- telephone number;
- address;
- trading name;
- permitted activities.
The FCA warns that unauthorised firms can use different names and that consumers should check whether the firm is authorised for the service being offered.
Also remember that not appearing on a warning list is not proof that a company is legitimate.
The absence of a warning and the presence of authorisation are two different things.
11. CRYPTO AND FOREX REQUIRE EXTRA CARE
Platforms operating around forex or cryptocurrency can expose investors to additional risks.
Forex
Leverage can magnify both gains and losses.
Cryptocurrency
Prices can be extremely volatile, and some transactions may be difficult to reverse.
Online investment platforms
Investors may have limited protections when dealing with firms that are outside the regulatory framework applicable to them.
The presence of sophisticated trading technology does not remove these risks.
12. WHAT INVESTORS SHOULD NEVER DO
Avoid these behaviours when dealing with an unfamiliar investment provider:
Do not borrow money because a representative promises a return.
Do not give a stranger remote access to your computer or phone.
Do not provide banking passwords or one-time security codes.
Do not send cryptocurrency simply because someone says the transfer is required for verification.
Do not make a second payment merely because someone says it will release your first payment.
Do not allow fear of missing out to replace due diligence.
13. IF YOU HAVE ALREADY INVESTED
If you have already deposited money with Intrade24, focus on preserving your position rather than trying to recover losses through another deposit.
Stop
Do not automatically send additional funds.
Preserve
Save screenshots, account statements and the complete communication history.
Record
Keep bank details, transaction references and payment receipts.
For cryptocurrency transactions, preserve wallet addresses and transaction hashes.
Contact
Notify your bank or payment provider promptly if you believe you may have transferred money to an unauthorised investment operation.
Report
Consider reporting the matter to the relevant financial regulator and fraud-reporting authority in your jurisdiction.
The sooner financial institutions are informed, the more useful the available information may be.
14. THE SECOND SCAM: RECOVERY FRAUD
After an investment loss, investors sometimes receive another unexpected offer:
“We can recover your money.”
This can come from someone claiming to be:
- a recovery agent;
- lawyer;
- blockchain specialist;
- government investigator;
- financial investigator;
- asset-recovery company.
The person may even know details about the original investment.
That does not establish that they are genuine.
Be particularly cautious if they demand:
- upfront fees;
- cryptocurrency;
- taxes;
- legal deposits;
- account-access credentials;
- remote computer access.
Never allow one financial loss to become the reason for another payment to an unverified party.
15. THE 60-SECOND INVESTOR CHECK
Before depositing money with an unfamiliar platform, ask:
| Question | What you need to establish |
|---|---|
| Who? | Exact legal company |
| Where? | Legal jurisdiction |
| Who regulates it? | Named financial regulator |
| Is it authorised? | Independent regulatory confirmation |
| What can it do? | Exact permitted activities |
| Where does my money go? | Verified payment recipient |
| Who holds it? | Custodian/bank information |
| How do I withdraw? | Clear withdrawal procedure |
| What happens if something goes wrong? | Complaint and protection arrangements |
| Am I being pressured? | If yes, stop and investigate |
If the answers do not line up, do not invest until they do.
FINAL VERDICT — WITHOUT THE HYPE
The most important fact about Intrade24.com is not what its website promises.
It is the fact that the AMF officially listed Intrade24 as a high-risk platform on 4 September 2026 and stated that it is not registered with the AMF or authorised to solicit Québec investors.
That does not justify declaring every activity connected with the platform fraudulent.
It does justify treating the platform as unverified and requiring substantial caution, particularly where investors are being asked to transfer money.

